The Canadian government unveiled a significant tax reform during the Canada Investment Summit, introducing a new measure called the productivity mega-deduction. This initiative allows businesses to deduct the full cost of investments in various sectors such as machinery, equipment, clean energy, and zero-emission vehicles.
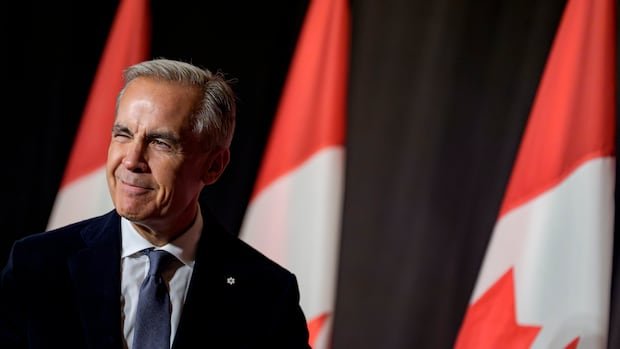
Prime Minister Mark Carney, speaking at the summit, expressed the government’s aim to position Canada as the most appealing destination for investment among G7 countries. The productivity mega-deduction expands on the previous productivity super-deduction introduced in the last year’s budget, which covered only a limited range of investments. With this enhancement, around two-thirds of assets will now qualify for the deduction.
The expansion to additional sectors provides business leaders with the flexibility to invest strategically and aims to enhance productivity, an area where Canada has historically struggled. This approach differs from a blanket corporate tax cut as it incentivizes reinvestment in Canada, ensuring that deductions are tied to new capital investments.
The government anticipates that this tax reform will reduce Canada’s marginal effective tax rate significantly, making it the lowest among G7 nations. This move is expected to encourage companies to remain in Canada, stimulate investment, and address uncertainties arising from trade conflicts. However, the program’s estimated cost of $36 billion over five years raises concerns about long-term sustainability and the need for careful fiscal planning.