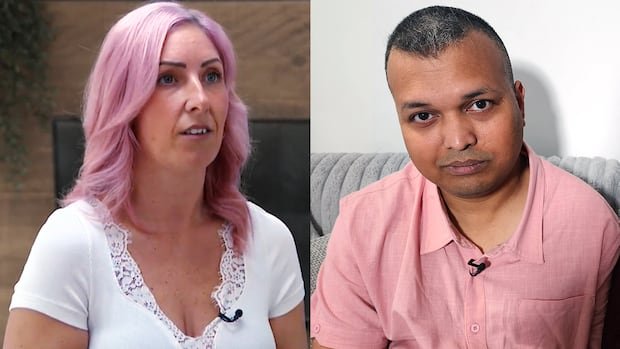
In the past year, two individuals reported falling victim to a financial scam in both Canada and the U.K. The distinguishing factor was their geographical location, which led to contrasting outcomes. Asif Mohammed from Canada lost $7,200 without full reimbursement, while Samantha Bradshaw from the U.K. was swiftly refunded £11,000 (almost $21,000 Cdn) by her bank.
Unlike Canadian banks, British financial institutions are mandated by law to compensate most scam victims promptly after a claim is made, ensuring a quicker resolution. This legal disparity means that British banks have a stronger incentive to combat fraud compared to their Canadian counterparts, as highlighted by a recent investigation by CBC’s Marketplace.
Mohammed, based in Toronto, encountered a fraudulent scheme during a project when he received a deceptive call purportedly from Tangerine, his bank. The caller, posing as a representative from Tangerine’s fraud department, informed Mohammed of unauthorized transactions on his debit card and arranged for its collection under false pretenses. Subsequently, money was siphoned from his account, leading to a realization of his grave error.
Conversely, Bradshaw in England faced a similar situation, enduring a distressing four-hour ordeal where her compromised cards were exploited by scammers. Despite the harrowing experience, Bradshaw’s bank swiftly covered the entire loss in compliance with the U.K.’s reimbursement regulations.
In the aftermath, Mohammed and his spouse engaged in protracted negotiations with Tangerine, culminating in a settlement that did not fully recoup their losses. While Tangerine refrained from commenting on this specific case, they emphasized their utilization of fraud prevention measures and client education to safeguard against illicit activities.
The contrasting approaches of Canadian and British banks regarding scam reimbursement reflect broader regulatory disparities. Industry experts suggest that shifting accountability from customers to banks enhances scam detection and prevention capabilities. British financial institutions, such as Santander, have bolstered their fraud detection mechanisms in response to reimbursement regulations, leading to more proactive anti-fraud measures.
Despite concerns about potential drawbacks such as transaction delays, British banks continue to fortify their defenses against scams through innovative technologies like machine learning and real-time monitoring. In cases of financial losses to scammers, the U.K. mandates shared reimbursement responsibility between sending and receiving banks, except in cases of gross negligence.
While the U.K. has made substantial strides in combating financial scams, the question remains whether Canada will adopt similar measures. In response to calls for Canadian banks to reimburse scam victims, Finance Minister François-Philippe Champagne outlined ongoing efforts to enhance consumer protection but stopped short of committing to bank liability. Champagne emphasized collaborative consultations with various stakeholders and the deployment of federal officers to combat fraud effectively.